The Buyer Advantage: Why Phoenix Buyers Are Getting More Today Than When Rates Were Lower
The Buyer Advantage: Why Phoenix Buyers are Getting More Today Than They When Rates Were Low
More than a new home. A stronger financial start.
When rates were under 3%, buyers secured a great rate and very little else. Bidding wars, waived inspections, offers over asking, and appraisal gaps paid in cash were the norm. The rate was the only win on the table.
Today, the rate is one piece of the puzzle. The rest of the puzzle is now working in the buyer’s favor.
Here is exactly what that looks like, using two of our most recent buyers.
Two Buyers, Two Loan Types, the Same Result
James | VA loan
Sheree | Conventional loan
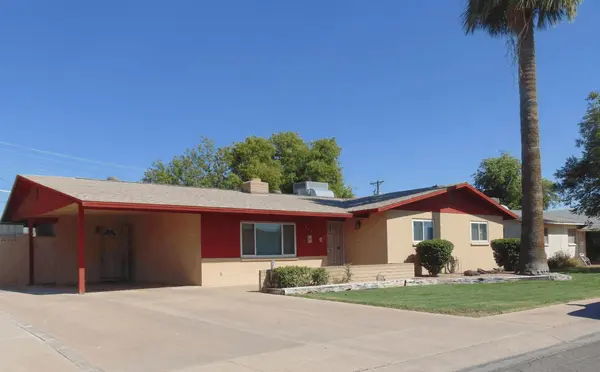
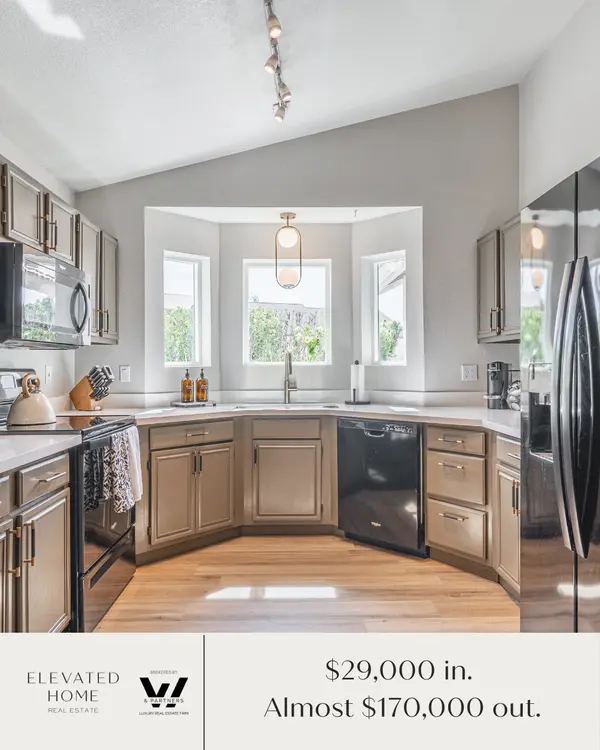
Both purchased homes in the Moon Valley area. Both put 5% down. Here is what we negotiated for each of them:
- Seller concessions | 3%, applied toward closing costs and a rate buydown
- Buyer broker fee | 3% paid by the seller
- Home warranty | Paid in part or in full by the seller
- Repairs | Completed and/or a portion of them paid for by the seller
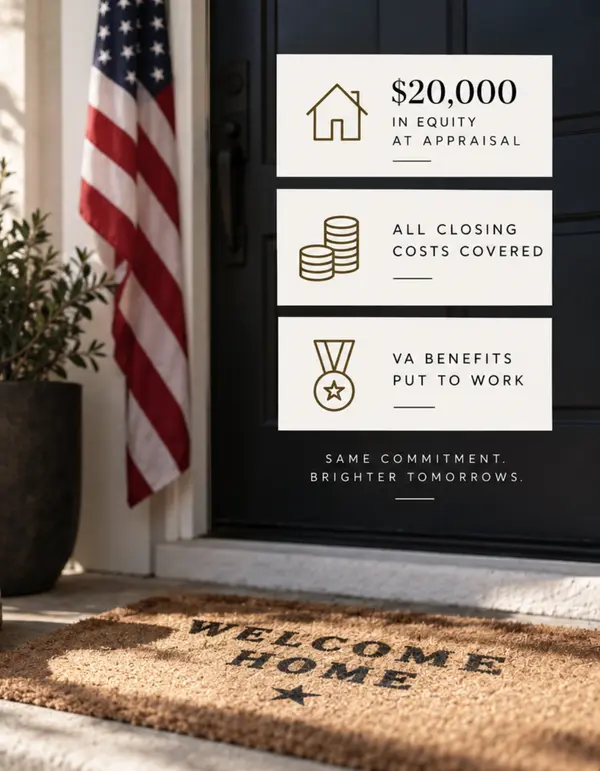
- Appraisal | Above purchase price, creating approximately $20,000 in equity on day one
Read that last line again. Both buyers walked in owning more equity than they put down.
These Terms Did Not Happen by Accident
None of these terms were requested by our buyers. They came from knowing the market and knowing where the leverage was.
Before writing each offer, we looked closely at what the data was telling us:
- How long the home had been on the market and whether the price had already been reduced
- What comparable homes had actually sold for, so we could set our offer price with confidence and anticipate the appraisal
- What sellers in the area were already offering, so we knew what was realistic to ask for
- How to structure the concessions so they worked hardest for each buyer, whether through a lower rate, lower cash to close, or both
Then we negotiated each piece intentionally. The concessions, the buyer broker fee, the home warranty, and the repairs were each part of a deliberate strategy, not an afterthought.
This is the difference an experienced advisor makes. Most buyers do not know these terms are available, and they should not have to. That is our job.
The Rate Is One Piece, Not the Whole Picture
I hear it often: “I’m waiting for rates to come down.”
The instinct is understandable, but it leaves out the full picture. When rates drop, buyers return and competition follows. Concessions disappear. Repairs become “as-is.” Appraisal gaps come out of the buyer’s pocket. Prices rise.
Today, buyers can:
- Buy down their rate using seller funds rather than their own
- Reduce cash to close through seller-paid concessions
- Negotiate repairs rather than inheriting them
- Have the seller contribute toward their agent’s fee, keeping more cash in their pocket
- Purchase at or below appraised value, starting with built-in equity
If rates fall later, refinancing is an option. You can change your rate. You cannot go back and change your purchase price.
VA Buyers: Your Benefit Goes Further Right Now
James used his VA loan, and it worked exactly the way it should. VA loans have their own guidelines for seller-paid costs and are often among the most flexible programs available. In a market where sellers are willing to negotiate, that benefit becomes even more powerful. If you have earned it, this is the time to put it to work.
First-Time and Conventional Buyers: Use Every Tool Available
Sheree had been renting for years and was ready to start building equity of her own. With a conventional loan and 5% down, she secured the full 3% in seller concessions allowed at that down payment, along with seller-paid repairs and a home warranty. She now owns more equity than she invested.
For first-time buyers, this market offers something that was rarely available a few years ago: room to negotiate.
Where We Are Seeing These Results
These opportunities extend throughout Central and North Phoenix, including Arcadia, the historic districts such as Encanto-Palmcroft, Willo, F.Q. Story, Coronado, Medlock Place, and Windsor Square, through North Central, and up into the Moon Valley area. These are established, character-filled neighborhoods where buyers typically face strong competition. Right now, there is room to negotiate.
The Buyer Advantage Is Here. What Are You Waiting For?
If you have been on the fence, here is the reality: buyers today are receiving more than they did when rates were lower. More negotiating power, more seller contributions, and more equity from day one.
My goal is to make this process seamless. My team and I will guide you through every step, work alongside a trusted lender to structure your financing, and make sure every available advantage is on your side.
Let’s talk about what’s possible for you. Book a call or reach me directly at 949.813.9144 or anna@elevatedhome.realestate.
Frequently Asked Questions
Is now a good time to buy a home in Phoenix?
For many buyers, yes. Sellers in Central and North Phoenix are offering concessions, rate buydowns, repairs, and contributions toward buyer agent fees that were rare when rates were lower.
Can sellers pay closing costs on a VA loan?
Yes. VA loans allow sellers to contribute toward closing costs and concessions, and the guidelines are often more flexible than other loan types.
Can a first-time buyer in Phoenix buy with 5% down?
Yes. Both buyers featured here put 5% down, and seller concessions helped reduce their cash to close.
What are seller concessions?
Funds the seller contributes toward your closing costs, prepaids, or a rate buydown, reducing what you bring to closing.
Who pays the buyer’s agent in Phoenix?
It is negotiable. In both examples here, the seller contributed 3% toward the buyer broker fee.
Should I wait for interest rates to drop?
Waiting may mean more competition and fewer seller concessions. You can refinance a rate later, but you cannot renegotiate your purchase price.
#TheBuyerAdvantage
Brokered by W & Partners, Elevated Home Real Estate. Results reflect specific transactions and are not a guarantee of future terms. Loan programs, concessions, and approval vary by buyer and lender.
Categories
- All Blogs (37)
- 3% Down Student Purchase (2)
- Acadia Lite (1)
- Architecture & Design (2)
- Arizona Real Estate Agent (6)
- ASU student housing (1)
- Before & After (2)
- Biltmore / Arcadia (1)
- Building Wealth (3)
- Buying Strategy (7)
- Buying vs. Renting (5)
- Case Studies (2)
- Central Phoenix (2)
- Central Phoenix Neighborhoods (3)
- Client Stories (4)
- client testimonials (2)
- Client Transformations (1)
- Coming Soon (1)
- Creative Financing, (2)
- Desert Ridge Real Estate (1)
- Elevated Living (1)
- Encanto Palmcroft (1)
- Encanto Palmcroft Phoenix (1)
- First Time Home Buyer (9)
- GCU Phoenix Housing (1)
- GCU student housing (2)
- Historic Home Expert (1)
- Historic Homes (2)
- historic Phoenix homes (2)
- Home Buying in Phoenix (7)
- Home Preperation (2)
- home remodeling Phoenix (1)
- Home Renovation (2)
- Home Renovation in Phoenix (2)
- How we get deals done (5)
- interior renovation (1)
- Investment Properties (3)
- Just Closed (4)
- Just Sold (1)
- kitchen renovation (1)
- Leasing & Tenant Placement (1)
- Lifestyle + Transition (1)
- Listing Preperation (2)
- market update (2)
- NAU Phoenix housing (1)
- negotiation (3)
- Neighborhood Guides (1)
- New Listing (6)
- Off-Campus Housing (2)
- Owner Resources (1)
- Phoenix homes for sale (1)
- Phoenix property tour (1)
- Phoenix Real Estate (11)
- Phoenix Real Estate Market (7)
- Phoenix Realtor (6)
- real estate for parents (1)
- Real Estate Insights (5)
- Real Estate Investing (3)
- Real Estate Stories (3)
- Real Estate Strategy (7)
- Real Estate Tips (1)
- Reflections and Gratitude (1)
- Remote & Out-of-State Landlords (1)
- Rentals in Phoenix (2)
- ROI (1)
- safe neighborhoods Phoenix (1)
- Sellers (1)
- staging (1)
- Starter Home Phoenix (2)
- Student & College Housing (2)
- student rental income (2)
- Thoughtful Living (1)
- UArizona Phoenix housing (1)
- University Area Housing (1)
- VA Buyer (3)
- Willo Historic District (1)
Recent Posts
GET MORE INFORMATION
Broker Associate License ID: BR651440000
+1(949) 813-9144 | anna@elevatedhome.realestate